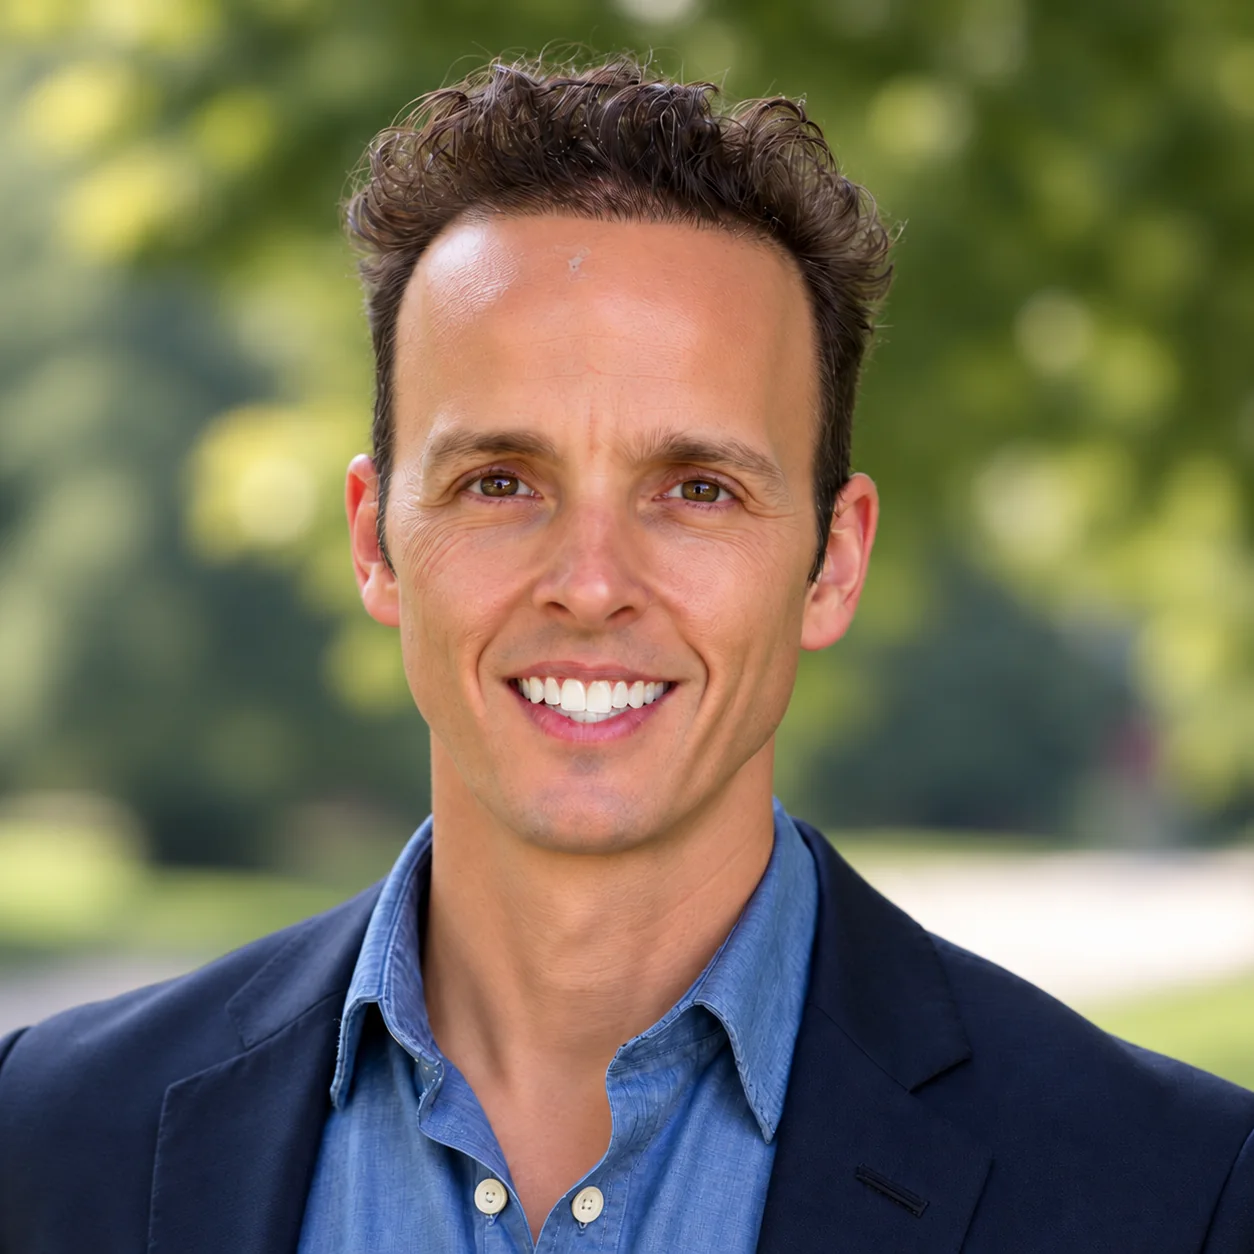
Experience across real estate, business and financing.
I help self-employed borrowers and real estate investors explore financing that fits how they earn, what they own and what they want to accomplish.
My background spans business ownership, real estate brokerage, construction and mortgage origination. I bring that perspective to the whole transaction: the property, the documentation, the funding and the closing.
A business owner's perspective. A transaction professional's experience.
2001
Real estate roots and online businesses
I first became licensed as a real estate salesperson in 2001. My early focus was entrepreneurship: building websites, working in search engine optimization and e-commerce, and using affiliate technology to help businesses generate online sales. Running businesses myself shaped how I understand borrowers whose income does not arrive as a regular paycheck.
2015–2019
Brokerage, investors and the full property cycle
I became more active in real estate in 2015 and went on to open a boutique brokerage in South Florida. By 2019, our investor work connected acquisitions, financing and resale. I helped investors find properties with improvement potential, coordinate business-purpose funding and list the completed properties for sale.
During those years, I also earned general contractor and roofing licenses. That work gave me practical experience with renovation scopes, contract administration, title-company closings and the details that can keep a transaction moving.
2023–today
Full-time loan origination
I began originating loans full-time in 2023. Helping investors obtain financing had led naturally to helping those same business owners buy homes to live in, using eligible income documentation beyond the traditional paycheck.
I moved from Florida to Tennessee in August 2024. As I focused on mortgage origination and made that move, I voluntarily relinquished my former Florida real estate broker, general contractor and roofing licenses or allowed them to expire. They are part of my experience; I no longer practice those professions in Florida.
TWO DISTINCT FINANCING PATHS
A home to live in. A property to invest in.
The purpose of the loan determines the path we take and the business you work with.
RESIDE · EDGE HOME FINANCE
Owner-occupied home financing
My home-loan work is through Edge Home Finance, LLC. Alongside conventional and FHA options, I focus on self-employed business owners, 1099 earners and independent contractors who may qualify using bank statements, profit-and-loss documentation or eligible assets.
Each program has its own documentation and underwriting requirements. We review the complete financial picture before choosing a path.
Luke Roasst · NMLS# 2311093 Owner-occupied financing through Edge Home Finance, LLC · NMLS# 891464
My business-purpose work is routed through KMN LLC, the company I own. I help property investors explore fix-and-flip, bridge, new-construction and DSCR rental financing, and compare other eligible documentation options when appropriate.
KMN stands for “Know My Name, Know My Number.” My phone number spells my name: 585-3-ROASST. It reflects how I work—direct access, clear communication and a relationship that can continue from one transaction to the next.
Luke Roasst · KMN LLC Business-purpose investment financing
Tell me the property state and intended use first. Availability depends on the applicable licensing, property and program; not every option is available in every state.
EXAMPLES FROM MY WORK
Start with the goal. Then compare the paths.
These are anonymized accounts of situations I have worked on, in my own words.
A self-employed refinance using P&L income documentation
I helped a business owner complete a $1.4 million refinance using a single-page profit-and-loss statement for income qualification. The point was to find an eligible way to document the business's income. A P&L used for income qualification does not replace the rest of the loan's credit, asset, property and underwriting requirements.
A rental purchase that needed a different approach
An investor purchasing a rented triplex could not reach the desired financing level under the initial DSCR option. I helped the investor move to an eligible bank-statement option, increasing financing from 75% to 80%. Comparing more than one qualification method helped address the investor's goal.
Planning a home purchase before selling the current home
I helped a homeowner plan to access equity in an existing home for the next purchase. We used a P&L-based qualification approach to account for both mortgage obligations during the transition, with the existing home to be sold after the move. The work involved coordinating income documentation, available equity and the timing of both transactions.
These examples describe individual situations, not standard terms or a promise of similar results. Eligibility, leverage, documentation, costs and timing vary. This is not a loan approval or commitment to lend.
WHAT WORKING WITH ME LOOKS LIKE
Useful technology. Reachable people.
I use technology to organize information and reduce repeated work, while staying accessible when you need to talk through a decision. For business-purpose borrowers, the KMN Investor Suite brings applications, documents and transaction information into one place to support an ongoing working relationship.
My goal is to make the next step understandable: what we need, why we need it and which options deserve a closer look.